Nobody keeps a home inventory until they need one — and by the time they need one, it's too late to make it properly. A fire, a flood, a burglary, a busted pipe that ruins a room: in the aftermath, an insurance adjuster asks a version of the same question. What did you actually have, and what was it worth? Answering from memory, standing in a house that's missing half its contents, is exactly as hard as it sounds. People forget entire categories of belongings, guess low on value, and can't produce the proof an insurer wants for anything expensive. A home inventory fixes all of that in advance, and building one is far less work than most people assume.
Why memory isn't good enough when it matters
Insurance claims run on documentation, not recollection. When you file a claim for lost or damaged belongings, the insurer isn't obligated to just take your word for what you owned — they want proof of ownership and a reasonable basis for value, especially for anything above a modest dollar amount. Without it, claims get lowballed, disputed, or partially denied, not usually out of bad faith but because there's genuinely nothing to check the number against. And memory is worse than people expect under the circumstances: after a loss, you're stressed, you're missing the visual cues a room normally gives you, and you tend to remember the obvious big items while entire drawers, shelves, and closets of smaller ones quietly vanish from the list. A little documentation done in a calm afternoon is worth far more than a detailed memory under pressure.
Start with a five-minute video walkthrough
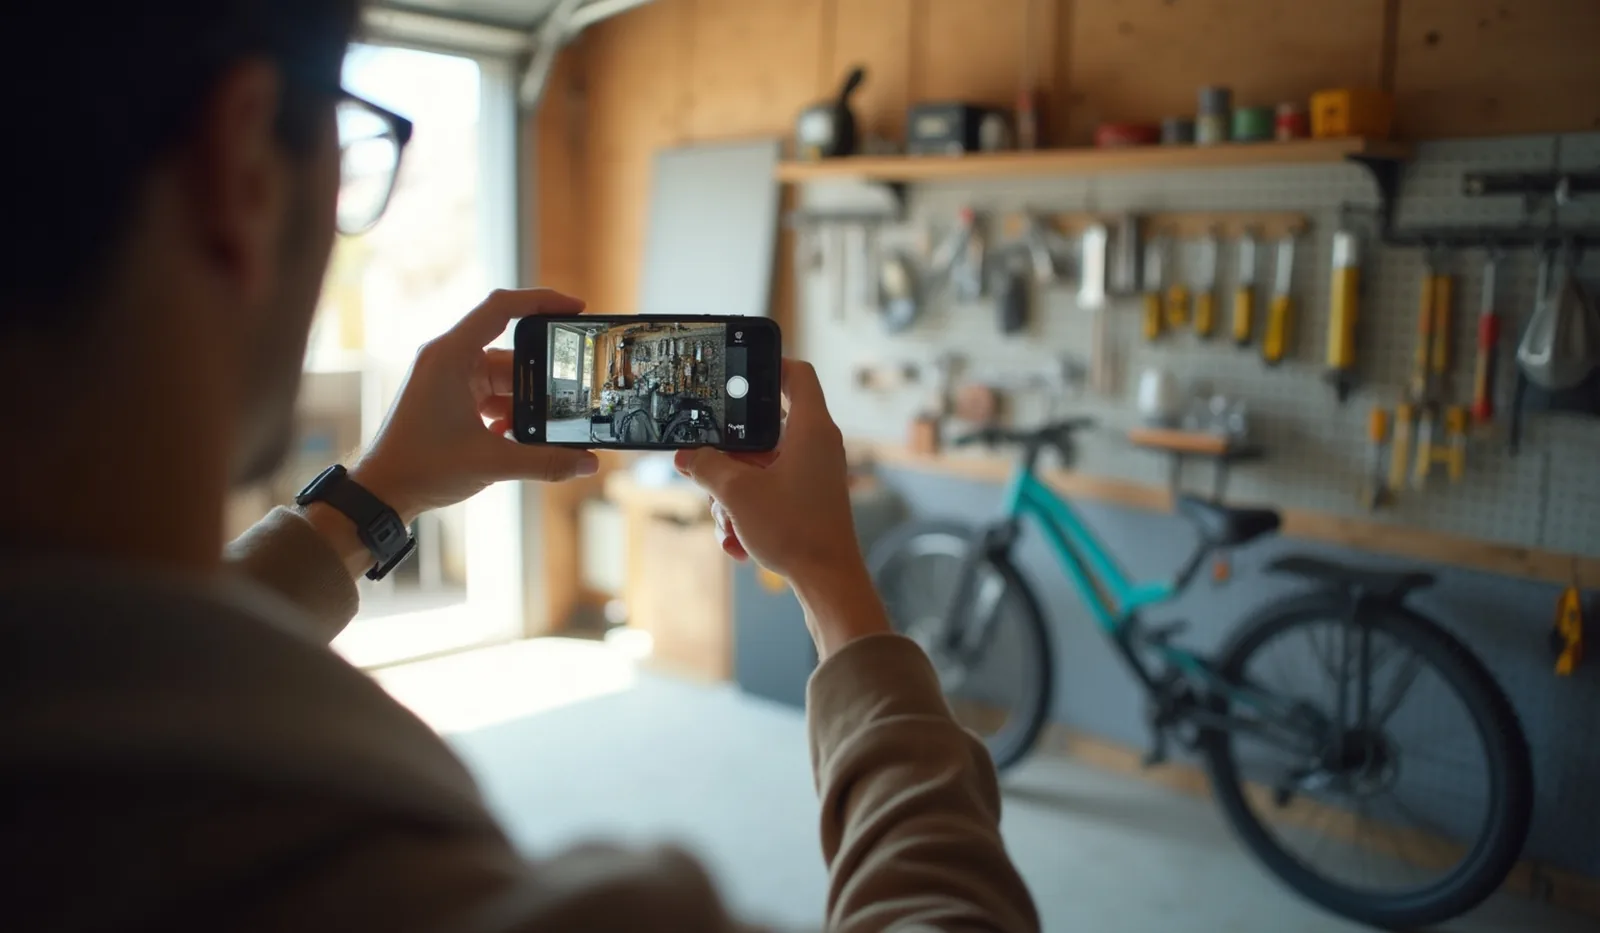
The fastest way to build a real inventory is also the easiest: walk through your home with your phone recording video, and narrate as you go. Open closets, drawers, and cabinets as you pass them, and say out loud, in plain language, roughly what's inside — “kitchen drawer, everyday flatware and the good knives,” “hall closet, coats and the vacuum.” Don't overthink it or aim for perfection; the goal is a baseline record that exists, not a museum catalog. One slow, narrated lap through the house, room by room, typically takes ten to fifteen minutes and captures the large majority of what an adjuster would ever ask about. Do it once as a starting point, then treat it as something you refresh rather than something you have to get exactly right the first time.
Go deeper on the big-ticket items
The video covers breadth; the expensive stuff deserves a second, closer pass. For anything genuinely costly — major electronics, large appliances, tools, jewelry, furniture, sports and outdoor gear — take an individual photo, and where the item has one, photograph the serial number or model tag too (usually a small sticker on the back or underside). Jot down roughly what you paid and when, even if it's an estimate, and keep any receipts you still have with the photo. This is the layer that actually matters when a claim is being negotiated: a general household video establishes that a room was furnished and lived-in, but a close-up of a specific item with its serial number and an approximate price is what turns a disputed line item into an approved one.
Where to actually store it (not just on your phone)
A home inventory that only exists on the phone sitting on your nightstand has a serious flaw: the disaster that destroys your belongings can destroy the phone right along with them. Back the video and photos up somewhere off-site the moment you take them — a cloud storage account works fine, a free tier is usually plenty of space for this, and turning on automatic photo and video backup means it happens without you thinking about it again. Emailing yourself a copy or saving one to a dedicated home-inventory app are both reasonable backups too. The point isn't the specific tool, it's that a copy exists somewhere you can reach from a hotel room or a relative's house, not just from a device that might be gone along with the house.
Keep it current without redoing the whole thing
An inventory that's five years stale is still far better than nothing, but it gets more useful the more current it is. You don't need to reshoot the whole house every time something changes — just build in a couple of light habits. Photograph and file the receipt any time you buy something genuinely expensive, the same day if you can manage it. Do a quick refresh pass once a year, walking the rooms that have changed the most rather than the whole house top to bottom. And when something significant leaves — sold, donated, replaced — a quick mental note (or an actual note) keeps the record honest instead of listing things you no longer own.
A few extra moves that help a claim
- Get real appraisals for standout items. Fine jewelry, art, or collectibles worth real money often need a professional appraisal and sometimes a separate policy rider — a phone photo alone won't carry the same weight for these.
- Check your coverage limits while you're at it. Building the inventory is a natural moment to notice if your policy's overall limit, or its cap on categories like electronics or jewelry, is actually enough to replace what you have.
- Don't skip the garage, attic, and storage unit. Tools, seasonal gear, and anything in off-site storage are exactly the categories people forget under stress — and exactly the categories worth a few extra minutes now.
None of this is exciting, and that's precisely why almost nobody does it until a loss forces the question. But the difference it makes is real and specific: instead of standing in a burned-out or flooded room trying to reconstruct what was there from memory, you open a folder that already has the answer — photos, serial numbers, rough values, all in one place, backed up somewhere the disaster can't reach. It's an afternoon of mildly tedious work that quietly protects every single thing you own.