Most budgets die the same way: you set a monthly number for groceries or eating out, life happens, and three weeks later you check your statement and discover you blew past it a week ago without noticing. The problem usually isn’t the number — it’s the timing. A normal budget only tells you the truth after you’ve already spent the money. The envelope method fixes that by moving the accounting to the front of the month instead of the back: you decide the limit before you spend a dollar, set that amount physically aside, and once it’s gone, it’s gone until the next cycle. No app has to catch you overspending, because the money to overspend simply isn’t there anymore.
Where the Envelope Method Comes From (and Why It Still Works)
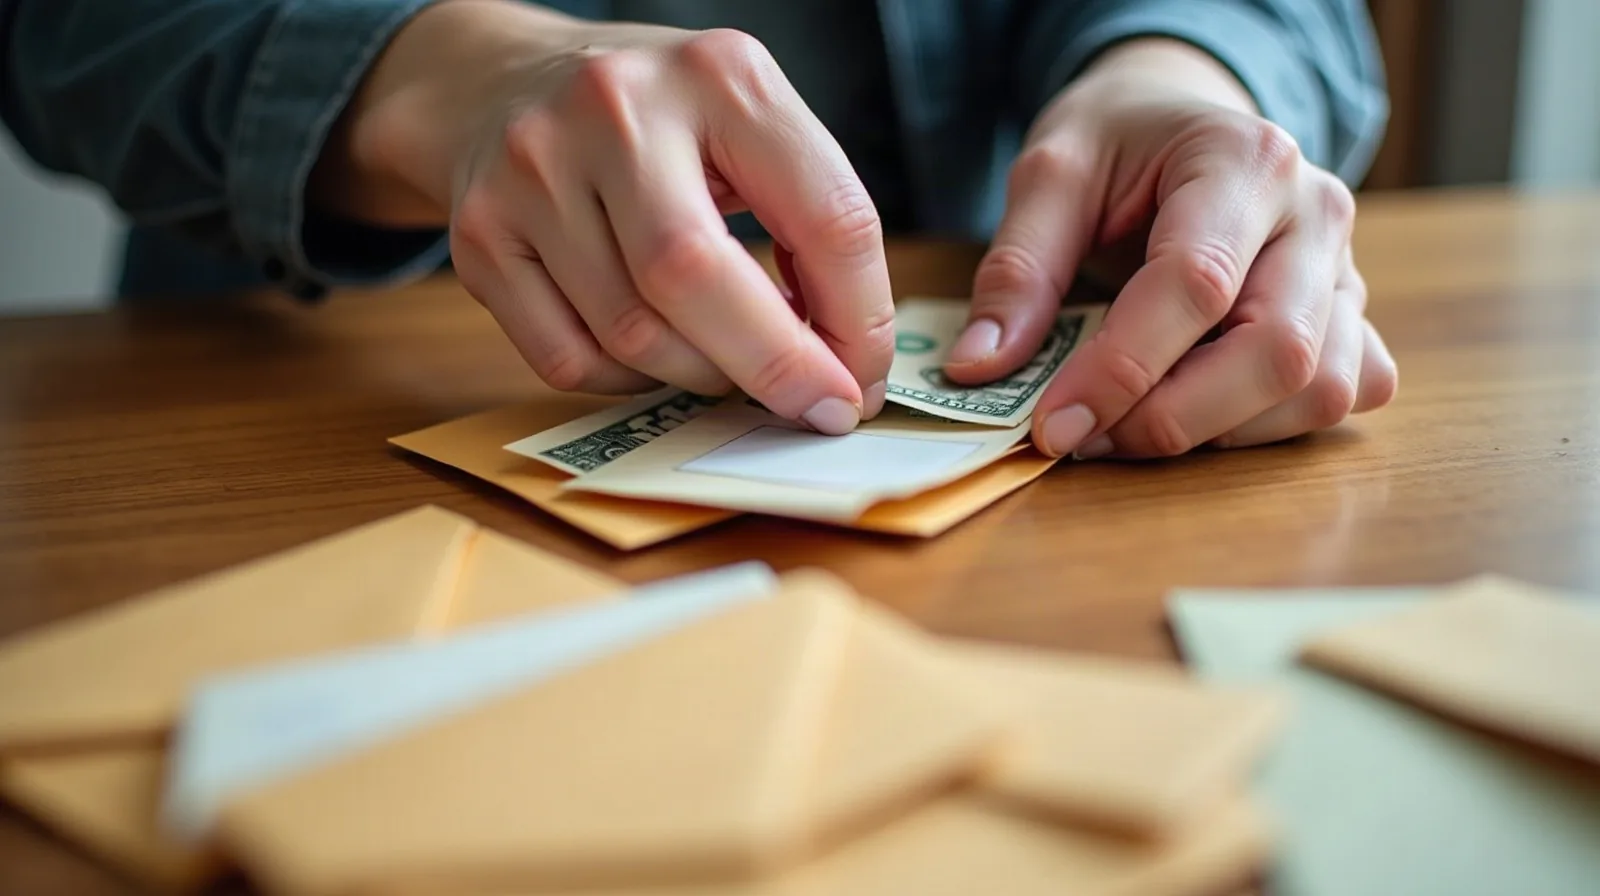
The idea predates budgeting apps by generations: cash for the week gets divided into paper envelopes, one per spending category, and each envelope only ever holds what’s allowed for that category. There’s no elegant trick to why it works — it works because a budget stops being a suggestion and starts being a physical constraint. A number in a spreadsheet is easy to argue with in the moment; an empty envelope isn’t. The method has survived because it solves the actual failure point of budgeting, which was never math — it was willpower at the exact moment of spending, when a spreadsheet is nowhere in sight but a wallet is.
Pick the Categories That Actually Leak Money
The envelope method only earns its keep on the spending that’s flexible and frequent — the categories where a little slippage every day adds up to a real overspend by month’s end. It’s the wrong tool for a fixed bill like rent or an insurance premium, which already has a set amount and a due date and doesn’t need a physical limit to behave. Keep the list short enough to actually manage:
- Groceries — the single biggest variable category in most households, and the one that’s hardest to track from memory.
- Dining out and takeout — almost always underestimated until it’s tallied up in one place.
- Gas or rideshare — predictable in total, unpredictable trip to trip.
- Personal or “fun” spending — the category every budget needs so the whole system doesn’t feel like punishment.
- Household odds and ends — the pharmacy run, the hardware store stop, the stuff that doesn’t belong anywhere else.
Four to six envelopes is the sweet spot. Fewer than that and one catch-all category hides too much; more than that and the system itself becomes a chore nobody keeps up with.
Real Cash or Its Digital Equivalent
Physical cash is still the purest version of this system, because a nearly-empty envelope is a feeling a screen can’t quite replicate — you can see and touch exactly what’s left. It’s worth trying in cash for at least one category, even if the rest of your spending stays digital, just to feel the difference. For everything else, most banking apps now offer named sub-accounts or savings “buckets” that work as digital envelopes: move the month’s grocery allowance into its own labeled balance, spend from a card linked to it, and watch that one number instead of your whole account. A budgeting app that supports category-based spending limits does the same job with less manual moving of money. What matters isn’t which version you pick — it’s that each category has its own visible, separate balance instead of blending into one big number that’s easy to lose track of.
The One Rule That Makes It Work: When It’s Empty, You’re Done
Every other budgeting method treats its category limits as guidelines you can quietly ignore under pressure. The envelope method only works because it doesn’t: when the dining-out envelope is empty, dining out is over for the cycle, full stop — no charging it to a card “just this once” and squaring it later, because later never quite happens. That hard stop feels restrictive the first month and becomes freeing by the third, because it removes the constant low-grade decision of whether you can afford something. The envelope already answered that question before you even asked it.
What to Do When You Run Short
Categories will occasionally come up short, especially in the first few cycles while you’re still calibrating the amounts. That’s useful information, not a failure. Borrowing from another envelope should be the rare exception rather than the default move — and when it happens, treat it as a debt owed back to that envelope next cycle, not a free pass. If the same category runs dry three cycles running, the fix isn’t more willpower, it’s a more honest number: raise that envelope’s amount and trim another one to match, so the total you’re setting aside each cycle stays the same even as the split between categories gets more accurate.
Reload on a Fixed Schedule (and Adjust Over Time)
Refill every envelope on the same schedule you get paid, with the same starting amounts each time, so funding the system becomes as automatic and unremarkable as paying a bill. Skip anything that’s already handled elsewhere — a fixed monthly bill has its own due date, and a once-a-year cost like an insurance premium or a holiday season is better solved by setting aside a little every month specifically for it, separate from this system entirely. Revisit the envelope amounts every month or two once you have a few cycles of real data: a category that’s always half-full at reload is over-funded, and that spare amount can move somewhere it’s actually needed.
None of this requires giving up your bank account or carrying a stack of cash everywhere — it requires giving your flexible spending real, visible limits instead of one blended number you only check after the damage is done. Start with three or four envelopes, real or digital, fund them on payday, and let the empty ones do the work a willpower-based budget never could.